
COMMENTARY:
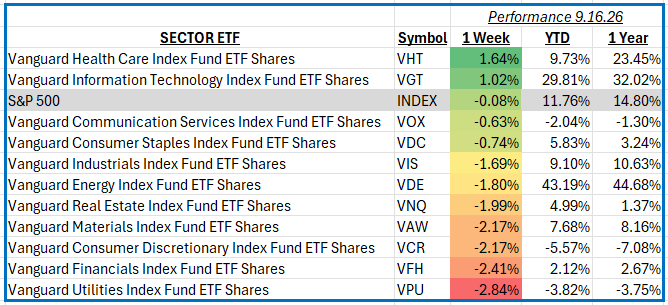
The S&P 500 finished the week essentially unchanged, returning -0.08% for the five trading days ended September 18. Markets were volatile as investors absorbed the Federal Reserve’s first rate increase since 2023. The Fed raised its target rate by 25 basis points to 3.75%–4.00%, citing still-elevated inflation, while signaling that additional tightening could be possible. At the same time, the 10-year Treasury yield approached 5% and crude oil remained above $100 per barrel, reinforcing concerns about inflation and borrowing costs.
Health Care was the strongest sector, rising 1.64%, or 1.72 percentage points ahead of the S&P 500. Strength was broad across pharmaceuticals and medical-device companies, with Johnson & Johnson, Merck, Regeneron Pharmaceuticals and Thermo Fisher Scientific among contributors. Investors continued to focus on clinical developments and drug pipelines, while health care’s more defensive characteristics provided support as broader markets dealt with higher interest rates and inflation concerns. Eli Lilly also remained an important area of investor attention, with its shares up 3.29% for the week.
Information Technology gained 1.02%, supported by renewed strength in semiconductor and AI-infrastructure stocks. Sandisk, Lumentum, Lam Research, Applied Materials and Broadcom were among the notable contributors. On Friday alone, Sandisk jumped 11%, while Lumentum gained more than 4%, and semiconductor stocks broadly benefited from renewed investor interest in AI-related capital spending. The sector’s resilience was notable given the week’s sharp increase in Treasury yields and renewed debate over the pace and sustainability of AI investment.
Communication Services declined 0.63%, with weakness concentrated in several large companies. Netflix fell 4.7% Friday following a Wells Fargo downgrade tied to concerns about engagement and its upcoming content slate. Other major companies in the sector, including Alphabet, Meta Platforms and Walt Disney, also faced a market environment in which higher interest rates placed pressure on growth-oriented valuations. (Barron’s)
Financials fell 2.41%, while Utilities declined 2.84%. Financials were hurt by concerns over slowing trading and investment-banking revenue, highlighted by Bank of America’s indication that third-quarter sales and trading revenue could be flat and investment-banking fees could decline. Utilities, meanwhile, were particularly sensitive to rising Treasury yields and finished 2.76 percentage points below the S&P 500, while also trailing Financials by 0.43 percentage points. NextEra Energy, Duke Energy, Southern and Dominion Energy all declined on Friday.
Overall, the week highlighted continued rotation beneath a nearly flat S&P 500, with Health Care and Technology providing leadership while higher rates pressured more interest-rate-sensitive areas of the market.
