COMMENTARY:
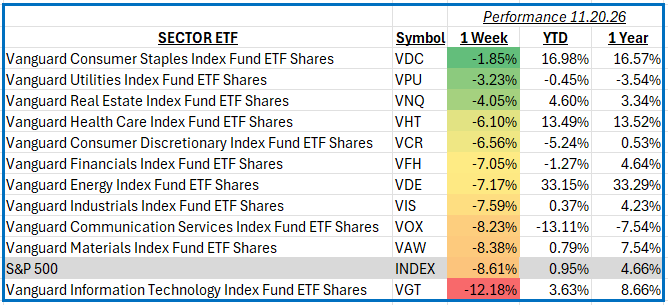
For the week ending November 20, 2026, the S&P 500 fell 8.61%, its steepest weekly decline in more than 18 months. A sharp selloff in artificial intelligence and semiconductor stocks drove much of the drop, and the index finished more than 10% below its recent high—a level commonly called a market correction. Nvidia’s strong earnings and upbeat outlook failed to calm investors, as concerns about the scale of AI investment and whether it will generate sufficient returns continued to weigh on technology shares.
Economic news added to the uneasy mood. Weekly jobless claims remained relatively low, suggesting layoffs were limited, while consumer sentiment stayed subdued amid persistent price pressures. Investors also weighed the possibility of higher interest rates, which can make future corporate earnings less attractive and increase borrowing costs.
Consumer staples held up best, declining 1.85%. Walmart and Costco, among the sector’s largest holdings, helped cushion the decline. Walmart’s results and outlook drew attention during the week, while investors generally favored companies selling everyday essentials as markets pulled back. Tyson Foods and Hormel Foods also advanced, providing support.
Utilities fell 3.23%, while real estate declined 4.05%. Both sectors performed better than the broad market, reflecting relatively resilient demand for utility services and steady investor interest in property companies. Within utilities, large holdings such as NextEra Energy and Southern Company were among the companies influencing sector results. In real estate, Prologis and Welltower are notable large holdings; individual property stocks also received support as Treasury yields eased late in the week.
Materials lost 8.38%, narrowly outperforming the S&P 500 by 0.23 percentage points. Information technology fell 12.18%, underperforming the index by 3.57 points and materials by 3.80 points. Nvidia and other chipmakers were prominent sources of pressure on technology, as investors continued to question the outlook for the AI trade despite strong reported results. Materials companies such as Freeport-McMoRan and Linde are among the sector’s major holdings, exposed to a difficult week for cyclical stocks.
Overall, defensive sectors proved more resilient, but broad selling made this a difficult week for investors.