
COMMENTARY:
The S&P 500 declined 0.47% for the week ending October 23, 2026, as concerns about artificial intelligence (AI) spending, rising oil prices, and geopolitical tensions weighed on investor sentiment. Markets experienced a midweek pullback following renewed questions about the profitability of massive AI investments, while escalating Middle East tensions pushed crude oil prices higher. Investors also assessed corporate earnings and economic indicators ahead of next week’s Federal Reserve meeting. The Dow Jones Industrial Average gained 0.4%, contrasting with declines in the S&P 500 and Nasdaq Composite.
Health Care, Energy, and Real Estate Lead
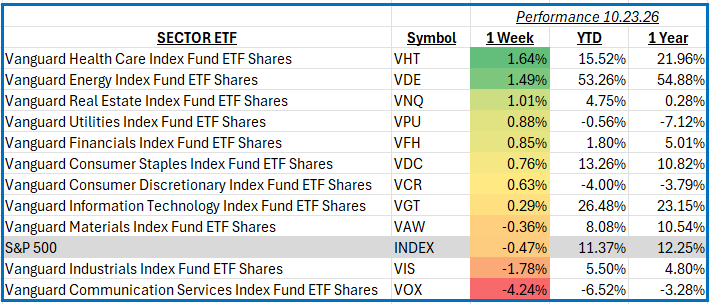
Health Care gained 1.64%, supported by demand for pharmaceutical, biotechnology, and medical technology companies. Pharmaceutical manufacturers, including Eli Lilly and AbbVie, remained in focus as investors evaluated earnings and growth prospects across the healthcare industry. The sector’s defensive characteristics also attracted investor interest amid broader market volatility. Energy advanced 1.49%, benefiting from rising crude oil prices as escalating tensions in the Middle East raised concerns about potential supply disruptions. Major integrated energy producers, including Exxon Mobil and Chevron, were positioned to benefit from the stronger commodity environment. Real Estate rose 1.01%, supported by its income-oriented characteristics and sensitivity to interest-rate expectations. Real estate investment trusts, including Welltower and Prologis, remained important contributors as investors evaluated financing costs, property demand, and the outlook for interest rates.
Industrials and Communication Services Lag
Industrials declined 1.78%, underperforming the S&P 500 by 1.31 percentage points. Weakness in industrial and transportation-related shares reflected concerns about economic growth, operating costs, and the broader market’s reaction to corporate earnings. Companies such as Caterpillar, Union Pacific, and GE Aerospace remained in focus as investors assessed business investment and industrial demand. Meanwhile, Communication Services fell 4.24%, making it the weakest of the five sectors highlighted. The sector underperformed Industrials by 2.46 percentage points and the S&P 500 by 3.77 percentage points. Meta Platforms declined following concerns about its expanding AI spending plans, while Alphabet also faced selling pressure ahead of its upcoming earnings report. Additionally, telecommunications shares tumbled after reports that SpaceX was considering launching another U.S. wireless carrier, raising competitive concerns for established providers AT&T and T-Mobile.
Market Outlook
Looking ahead, investors will focus on earnings from major technology companies, including Microsoft, Alphabet, and Amazon, alongside the Federal Reserve’s upcoming policy decision. Corporate guidance on AI investment returns, energy prices, and interest-rate expectations will remain important market drivers.
Closing Thoughts: Markets ended the week lower as investors balanced selective opportunities in defensive sectors against concerns about AI spending, geopolitical risks, and rising energy costs. Earnings and the Federal Reserve meeting could shape the market’s direction in the week ahead.
